Many of the most important financial decisions in retirement occur outside investment markets. Tax outcomes, family assistance and lifestyle choices can have a lasting impact on retirement security. This edition highlights practical strategies and common pitfalls that retirees and pre-retirees should consider when making financial decisions that affect both themselves and future generations.
The Tax Return in Retirement
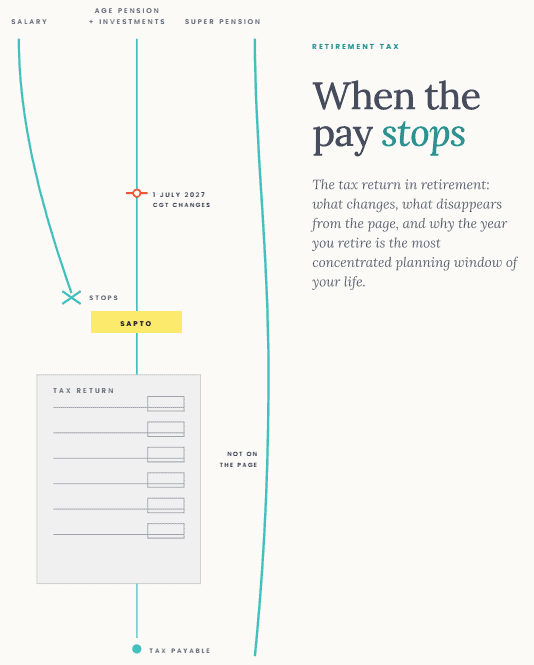
Retirement changes tax from an automatic payroll deduction into a series of decisions about income, capital gains and timing. Super pension income from a taxed fund is generally tax-free after age 60 and often does not appear on a tax return. The retirement year creates valuable planning opportunities because lower taxable income can reduce the impact of capital gains and other assessable income. Retirees should also understand the capital gains tax changes commencing 1 July 2027 and how transitional rules apply to existing assets.
Helping the Kids into a Home
Parents often want to help children purchase their first home, but the best solution is not always a cash gift. Gifts, family loans and guarantees each create different outcomes for Centrelink benefits, estate planning and family law protection. A properly documented family loan may provide more protection than an informal transfer of money. Families should consider their retirement security before committing substantial assets to help children enter the property market.
When the Kids Come Home Again
More adult children are returning home because of housing costs, relationship breakdowns and financial pressures. Parents should clearly define the purpose and timeframe of any living arrangement before it becomes open-ended support. Unplanned assistance can delay downsizing, increase retirement spending and extend working lives. Families who communicate expectations clearly are more likely to avoid future financial and estate disputes.
Q & A
- Why did my Age Pension increase by less than the headline amount?
Higher deeming rates reduced the benefit of the September pension increase for some part-pensioners.
- When should I lodge my Age Pension claim?
You can lodge up to 13 weeks before eligibility and should prepare documents early to avoid delays.
- Can an attorney use a parent’s money to help their own child buy a home?
Usually not, because attorneys must act in the principal’s interests and avoid conflicts of interest.
- Why did I receive a Division 296 letter if my super is under $3 million?
The ATO assesses balances across all super accounts and may write to members near the threshold.
- Should I consolidate multiple super funds?
Consolidation often reduces fees, but insurance and defined benefit entitlements should be reviewed first.