Retirement planning does not end when work finishes. In many respects, the decades that follow require ongoing attention to estate planning, insurance, financial administration and future care arrangements. This edition examines the importance of maintaining your financial affairs as circumstances change, from reviewing insurance needs to preparing for later-life decisions and transitions. By addressing these issues proactively, you can help protect your independence, simplify matters for your family and improve your long-term financial wellbeing.
Insurance After the Mortgage Is Gone
Many insurance policies remain in place long after the financial risks they were designed to cover have changed or disappeared. Retirement creates an opportunity to review each policy and determine whether it still serves a clear purpose within the household’s financial plan. The decision to keep or cancel cover should consider current needs, future costs, and the ability to replace cover later if circumstances change. Asking the right questions can turn insurance from an automatic expense into a deliberate and informed financial decision.
What a Financially Healthy 70-Year-Old Looks Like
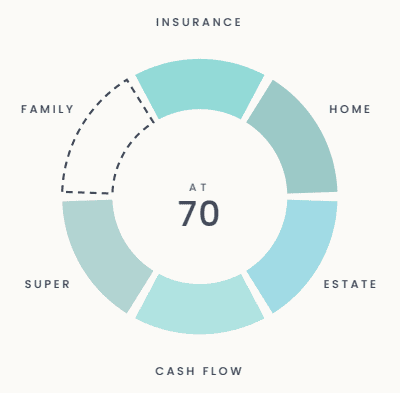
Financial wellbeing at age 70 is often less about wealth and more about having important decisions documented, organised and regularly reviewed. A financially healthy household understands its superannuation, estate planning, insurance, cash flow, housing and succession arrangements. Small administrative gaps can create significant problems later if documents, nominations or household records are not kept current. Regular reviews help ensure financial affairs remain aligned with changing circumstances and future needs.
The Second Half of Retirement
Retirement planning often focuses on the years immediately after leaving work while giving less attention to the decades that may follow. The years after 75 bring important decisions around housing, care needs, financial management and maintaining independence. Planning for these stages early can make future transitions more manageable and reduce stress for both retirees and their families. Viewing later retirement as a series of predictable planning milestones helps create greater confidence and preparedness.
Q & A
- What happens to our Age Pension if my partner moves into residential care?
Illness-separated couples can generally receive the single Age Pension rate while continuing to have their income and assets assessed together.
- Is a funeral bond treated differently to a prepaid funeral?
A prepaid funeral is fully exempt from the assets test, while a funeral bond is only exempt up to the allowable indexed limit.
- What happens to my online accounts when I die?
Access to digital assets is largely governed by platform rules, making legacy contacts and account records important estate planning tools.
- Can a bank freeze a joint account after my spouse dies?
Joint accounts usually continue under survivorship rules, although some account structures may result in temporary restrictions.
- Is an interstate enduring power of attorney still valid?
Interstate enduring powers of attorney are generally recognised, although practical issues can arise with institutions and differing state rules.