10 Years to Retirement
Massey Financial Advice
At Massey Financial Advice, we work with individuals and couples across Brisbane to help them navigate this critical decade with clarity and purpose. We bring together all the pieces – superannuation, debt, cashflow, insurance, estate planning, and more to create a retirement plan that supports your ideal lifestyle.
Make the Most of the Decade Before You Retire
The final ten years before retirement can be one of the most important periods in your financial life.
You may still have time to build your superannuation, reduce debt, review your investments and make decisions that could improve your retirement position. It is also the point when retirement often changes from a distant idea into something you need to plan for properly.
At Massey Financial Advice, we help individuals and couples across Brisbane understand whether they are on track and what they can do during their remaining working years to strengthen their position.
Through personalised advice and practical financial modelling, we can help you answer questions such as:
- When could I realistically retire?
- How much income might I have?
- Am I contributing enough to superannuation?
- Should I prioritise my mortgage or super?
- What lifestyle could my assets support?
- What changes could improve the outcome?
The aim is to give you a clear plan for the years ahead rather than waiting until retirement is almost upon you.
Why Planning Ten Years Before Retirement Matters
Ten years can provide enough time to make meaningful changes, while retirement is close enough that your decisions need to become more deliberate.
During this period, you may have opportunities to:
- increase your retirement savings;
- reduce or eliminate debt;
- make better use of your income;
- review how your superannuation is invested;
- prepare for major future expenses;
- reconsider your preferred retirement age;
- plan a gradual transition out of work;
- protect yourself against unexpected changes.
A retirement projection may show that you are already in a strong position. Alternatively, it may show that working a little longer, increasing contributions, reducing debt or adjusting planned spending could produce a more sustainable outcome.
The earlier you understand your position, the more choices you may have.
Are You on Track to Retire?
Many people approaching retirement have accumulated valuable assets but still do not know whether those assets will support the life they want. You may own a home, have superannuation and earn a good income, but still be uncertain about:
- how much you currently spend;
- how much you may spend after work;
- how long your savings might last;
- whether your investment strategy is appropriate;
- whether you can retire before 65;
- whether you may qualify for the Age Pension;
- what would happen if your circumstances changed.
A useful retirement plan brings these factors together and helps you see how they may interact over time.
Financial modelling cannot predict the future with certainty, but it can help you assess whether your current direction appears sustainable and compare the likely impact of different decisions.
For broader information about retirement advice, visit our Retirement Planning Brisbane page.
Our 10 Years to Retirement Approach
At Massey Financial Advice, we guide you through a practical, personalised planning process – free of judgement and full of clarity.
We start with a conversation to understand your goals, then build a plan that bridges where you are now with where you want to be.
Our goal is simple: help you retire with confidence, not guesswork. Whether retirement is five, ten, or even more years away, the right plan can make all the difference.
What to Focus on During the Final Ten Years
1. Understand Your Current Position
The first step is establishing where you are today.
This may include reviewing your:
- superannuation;
- savings and investments;
- home and other property;
- mortgage and other debts;
- income and household spending;
- personal insurance;
- expected future expenses.
Looking only at assets can give an incomplete picture. Your debt, spending and future commitments also need to be considered.
2. Define the Retirement You Want
It is difficult to determine whether you are financially prepared until you have some idea of what you are preparing for.
You may need to consider:
- when you would like to retire;
- whether you want to stop work completely or reduce your hours;
- where you plan to live;
- how often you would like to travel;
- whether you intend to downsize;
- major purchases or renovations;
- support for children or grandchildren;
- future health and care costs.
A comfortable retirement means different things to different people, so the plan needs to reflect your goals rather than a generic target.

3. Estimate Your Future Spending
Your current spending can provide a useful starting point for estimating your retirement income needs.
Some expenses may fall when you stop working, while others may increase. You may spend less on commuting but more on travel, hobbies, healthcare or home maintenance.
Your plan should consider:
- essential household expenses;
- discretionary spending;
- travel and leisure;
- vehicle replacement;
- health-related costs;
- larger one-off expenses;
- an emergency cash reserve.
This provides a more realistic basis for working out how much retirement income you may need.
4. Develop a Plan for Debt
Entering retirement with less debt may reduce the amount of income you need and provide greater flexibility.
However, deciding whether to repay debt faster is not always straightforward. You may also be considering whether to:
- make extra mortgage repayments;
- direct more income into superannuation;
- retain cash outside super;
- sell an investment asset;
- downsize your home;
- restructure existing loans.
The right balance depends on your interest rates, tax position, cash flow, retirement timeframe and need for access to funds.
5. Review Your Superannuation Strategy
Your remaining working years may provide an important opportunity to strengthen your superannuation position.
Depending on your circumstances, this may involve reviewing:
- salary sacrifice;
- personal contributions;
- unused concessional contribution opportunities;
- spouse contributions;
- multiple super accounts;
- fees and insurance;
- investment options;
- beneficiary nominations.
Contributing more to super may provide benefits, but it should be considered alongside debt, cash reserves and other goals.
6. Review Your Investment Risk
Being ten years from retirement does not necessarily mean all investment risk should be removed.
Your retirement may last for decades, so your assets may still need to provide long-term growth. At the same time, a large market fall close to retirement could affect your plans.
We can help you review:
- your mix of growth and defensive assets;
- diversification;
- the level of risk you are taking;
- how your investments align with your retirement date;
- how much cash or defensive assets may be appropriate.
7. Review Your Insurance
Your insurance needs may change as you approach retirement.
You may have less debt, older children and greater savings than when your cover was first arranged. However, losing your income unexpectedly during the final years of work could still affect your retirement plans.
A review may consider:
- whether your cover remains suitable;
- whether policies overlap;
- the cost of premiums;
- insurance held through super;
- how long cover may still be needed.
Insurance should not be reduced or cancelled without considering the financial consequences.
8. Decide How You Want to Stop Working
Retirement does not need to happen on one fixed date.
Some people prefer to:
- continue working full-time;
- gradually reduce their hours;
- move into a less demanding role;
- begin consulting or casual work;
- retire earlier because of health or redundancy.
Your preferred approach can affect your income, superannuation contributions, investments and retirement timing.
9. Prepare for the Unexpected
A retirement plan should not rely on everything going exactly as expected.
Your circumstances may be affected by:
- redundancy;
- illness or injury;
- caring responsibilities;
- family support;
- market downturns;
- rising living costs;
- changes to superannuation or pension rules;
- retiring earlier than planned.
We can model different scenarios and help build flexibility into your plan.
10. Review Your Estate Planning
Estate planning should be considered alongside your broader retirement strategy.
This may include reviewing your:
- Will;
- enduring powers of attorney;
- superannuation beneficiary nominations;
- jointly held assets;
- trusts or business interests.
Legal documents should be prepared or reviewed by an appropriately qualified legal professional. We can work with your solicitor and accountant to help coordinate the financial parts of your plan.

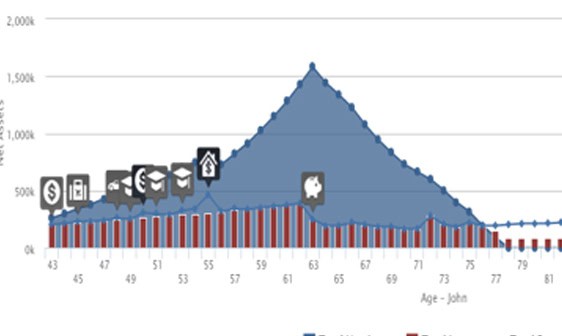
They are currently aged 43 and 41 respectively, plan to work until age 63, and according to Australian averages they can expect to live until 82 and 86.
The blue shaded area to the left of the peak shows how they are building assets while they are working. The icons and rising expenditure line show various expenses during this time which include…
- Overseas holidays every 3 years
- Replacement car every 5 years
- Private high school fees for 3 children from John’s age 49
- Purchasing a boat at age 50
- Home renovations at age 55
The spot where the blue net assets line meets the horizontal axis indicates when John and Sue will run out of money (around age 78). This gives them the opportunity to adjust their planning to achieve a different outcome. For example they could…
- Reduce their expenditure by changing or postponing some goals
- Become more disciplined with their spending (now and in the future)
- Modify their savings levels
- Adjust their investment risk
With this information, John and Sue can make decisions that help them prepare for retirement, balanced with current spending and life experiences.
Imagine having this financial modelling for your income, expenditure, and assets. Like John and Sue, it would help you to see how your current decisions will affect your future finances (and potential lifestyle).
This is just part of the process we use to help you plan for your future, adjust for changing circumstances, and stay on track to getting the outcomes you want. And it’s a key part of our ongoing service at our goal progress meetings.
Note: This case study is illustrative only and is not an estimate of the investment returns you will receive or fees and costs you will incur
How Financial Modelling Can Help
Retirement planning involves many connected decisions. Financial modelling allows us to compare them within one broader picture.
For example, consider a Brisbane couple aged 55 and 57 who would like to retire in approximately eight years.
They have superannuation, a remaining home loan, personal investments and plans to travel after retirement.
They may want to compare:
- retiring at 62, 65 or later;
- contributing more to superannuation;
- paying down the mortgage faster;
- reducing working hours before retirement;
- selling or retaining an investment;
- spending more during the early retirement years.
Modelling these alternatives can help show how their retirement date, income and assets may be affected.
It is not a guarantee of future outcomes, but it can provide a clearer basis for making decisions and understanding the trade-offs involved.
Our Ten Years to Retirement Process
1. Clarify your retirement goals
We discuss when you would like to retire, what you want retirement to look like and the questions you need answered.
2. Review your financial position
We consider your superannuation, assets, debt, income, spending, investments and insurance.
3. Project your current path
We model how your position may develop if you continue with your existing approach.
4. Compare alternative strategies
Where appropriate, we test different retirement dates, contribution levels, debt repayments, investment approaches and spending assumptions.
5. Develop your retirement roadmap
We set out practical priorities for the years ahead so you know what to do now and what should be reviewed over time.
6. Review your progress
Your plan can be updated as your income, goals, family circumstances and preferred retirement date change.
What If Retirement Is Less Than Ten Years Away?
You do not need to be exactly ten years from retirement to benefit from planning.
Whether retirement is five, eight or fifteen years away, understanding your current position may help you use the remaining time more effectively.
If you are within the final few years before leaving work, your priorities may be shifting towards:
- confirming your retirement date;
- accessing superannuation;
- establishing retirement income;
- building cash reserves;
- adjusting your investments;
- considering government entitlements.
Visit our Commencing Retirement page for more information about preparing for the transition out of work.
Ten Years to Retirement FAQs
What should I do ten years before retirement?
Start by reviewing your full financial position, clarifying your preferred retirement date and estimating the lifestyle you want to fund. You can then assess your superannuation, debt, investments, insurance and spending.
How do I know whether I am on track?
Financial modelling can compare your current assets and expected future savings with your likely retirement spending and income needs.
How much superannuation should I have?
There is no single balance that applies to everyone. The amount you may need depends on your retirement age, spending, housing, debts, other assets and future contributions.
Should I pay off my mortgage or put more into super?
Both options may improve your position. The right balance depends on your interest rate, tax position, cash reserves, contribution eligibility and retirement timeframe.
Is ten years enough time to improve my position?
Ten years can provide meaningful opportunities to increase savings, reduce debt, review investments and adjust your retirement plans.
Can I reduce my work hours before retiring?
Potentially. A gradual reduction in work can be included in your financial projections to assess how lower income and contributions may affect your plans.
Is it too late if I am only five years from retirement?
No. There may still be valuable decisions to make around superannuation, debt, investments, spending and retirement timing.


About Adam Massey
Adam Massey, founder of Massey Financial Advice, is a Certified Financial Planner® with a Bachelor of Business and a Diploma of Financial Planning. He is married to Bron, they have 3 children and Adam has lived in Sydney, Adelaide, Canberra, Port Douglas, London and now Brisbane. He was an active committee member of The Mater Foundation and volunteers at the school tuckshop. In other words, he has more than textbook knowledge – he has the formal training and life experience to help you get the financial outcomes you want – to build wealth for retirement without sacrificing your current lifestyle.
Graduate
Australian Institute of Company Directors
Why Work With Massey Financial Advice ?
Adam Massey is a Certified Financial Planner® with a Bachelor of Business and a Diploma of Financial Planning.
Brisbane has been Adam’s home for more than 20 years. Through Massey Financial Advice, he helps individuals and couples make practical decisions about retirement, superannuation, investments and their broader financial future.
Our approach includes:
- personalised advice;
- practical retirement modelling;
- clear explanations without unnecessary jargon;
- realistic strategies rather than generic targets;
- regular reviews as retirement approaches.
The aim is to help you understand where you stand, what options are available and what actions may improve your position.
What Others Are Saying…
Here is a small sample of what other people say about their experience dealing with Adam.
How to Explore Working Together
Would you like to know exactly how much money you’ll have when you retire based on your current plan? Would you like to know how to fast-track this plan so you can retire earlier and with more money? Would you like to know how an upcoming decision will affect this plan?